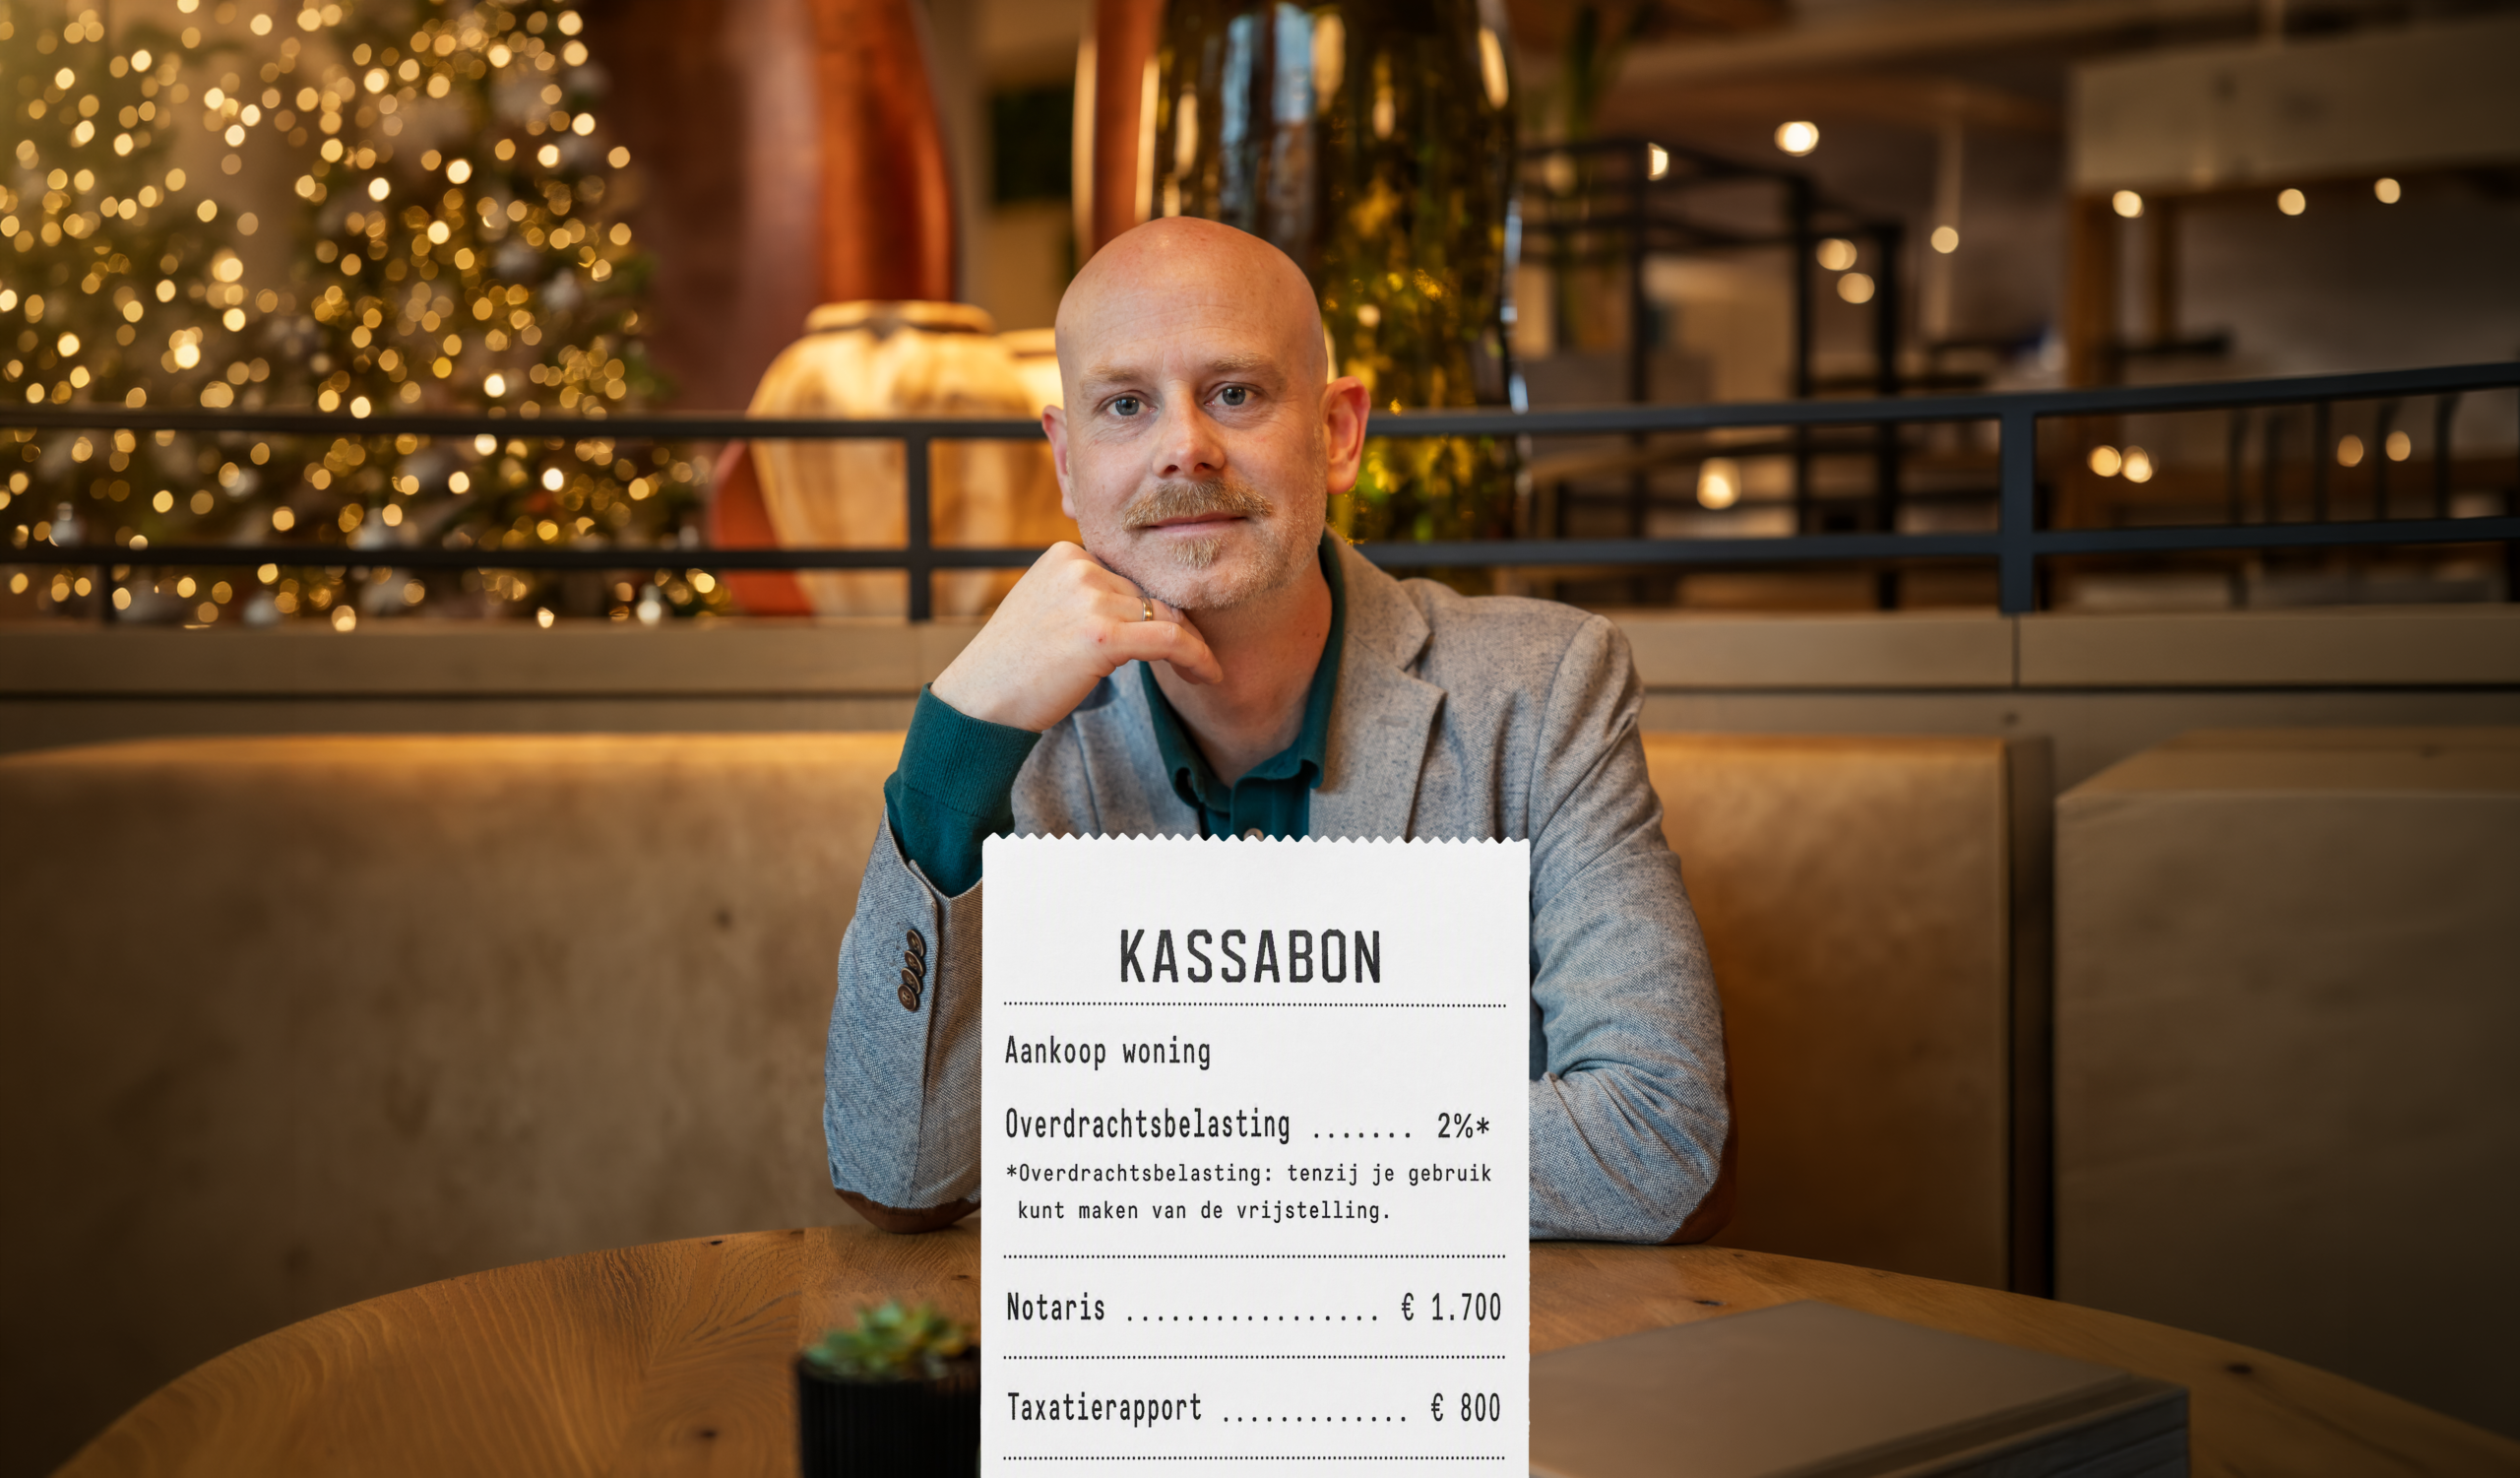
What does a property really cost?
Many homebuyers focus on the asking price. However, that is a mistake.
When you view a property, everything often revolves around the asking price. Can you make an offer? Does the property fit within your mortgage? And what will the monthly costs be?
But the purchase price only tells part of the story. Many buyers discover during the purchasing process that they need thousands of euros extra for costs that are not immediately visible. Consider notary fees, appraisals, advisory costs, sustainability improvements, and future maintenance costs. These so-called invisible purchasing costs are often the reason a purchasing budget comes under pressure.
In this blog, we explain which costs you can expect, how much of your own capital you will likely need, and how to avoid financial surprises.
Many buyers discover during the purchasing process that they need thousands of euros extra for costs that are not immediately visible. Consider notary fees, appraisals, advisory costs, sustainability improvements, and future maintenance costs.
These so-called invisible purchasing costs are often the reason a purchasing budget comes under pressure.
In this blog, we explain which costs you can expect, how much of your own capital you will likely need, and how to avoid financial surprises.
Why many homebuyers miscalculate the total costs
We increasingly see buyers confusing their maximum mortgage amount with their total spending capacity. And that is, incidentally, very understandable.
Online calculation tools often show how much you can borrow, but not always which costs you must pay yourself in addition.
In practice, a property of €400,000 often costs significantly more than just that €400,000.
Therefore, a good mortgage advisor looks not only at the financing but also at:
• Your total living costs
• Future plans
• Risks
• Savings
• Sustainability wishes
• Maintenance costs
What are the hidden purchasing costs?
Purchasing costs payable by the buyer (k.k.)
With existing properties, you will almost always have to deal with ‘purchasing costs payable by the buyer’.
These include:
• Transfer tax
• Notary fees
• Land registry fees
Many first-time buyers think these amounts can be included in the mortgage. However, that is by no means always possible.
For this, you often need to bring your own funds to the notary.
A practical example:
You buy a property for €350,000. When all additional costs are included, the amount you have to pay yourself can range between €6,000 and €14,000.
For many first-time buyers, this comes as a surprise.
Appraisal costs: An appraisal report is required for almost every mortgage. An appraiser determines the market value of the property. The lender uses this value to assess the risk the financing poses. Although an appraisal is only one part of the purchasing process, this expense is regularly forgotten in the budget.
Mortgage advice and mediation: Taking out a mortgage is much more than just comparing interest rates. Consideration is given to:
• Income
• Future plans
• Risks
• Insurance
• Sustainability improvements
• Taxes
• Fixed-interest period
Good advice often yields much more than just a competitive interest rate.
Building inspection; A property can look beautiful during a viewing. Yet, there may be hidden defects. Consider:
• Wood rot
• Roof problems
• Overdue maintenance
• Structural damage
With a building inspection, you gain more insight into the state of the property and the future costs. Especially with older homes, this can prevent thousands of euros in surprises.
Sustainability costs: Sustainability plays an increasingly large role in the purchase of a property. Not only because of lower energy costs, but also because properties with a better energy label are often more attractive in the long term. Examples of sustainability improvements:
• Roof insulation
• Wall insulation
• Floor insulation
• HR++ glass
• Triple glazing
• Solar panels
• Heat pump
Moving and furnishing costs: These are perhaps the most underestimated costs. Many people reserve money for the property itself, but forget costs for:
• Moving company
• Flooring
• Painting
• Lighting
• Window coverings
• Furniture
• Landscaping
Maintenance costs after purchase: The costs do not stop after the transfer of ownership. Every property requires maintenance. Consider:
• Painting
• Roof maintenance
• Central heating system
• Ventilation system
• Window frames
• Bathroom or kitchen
Older properties, in particular, often require a financial buffer. A good guideline is to always keep savings available for unexpected expenses.
The biggest pitfall
Many first-time buyers first find out the maximum they can borrow. Only then do they look at all the additional costs.
Our tip is: turn this around!
The most important question is not: “How much can I borrow?”
But:
“Which property fits my financial situation, now and in the future?”
How do you avoid financial surprises?
Before you buy a home, it is wise to answer the following questions:
1. How much of my own money do I have available?
Get a clear picture of how much savings are available for additional costs.
2. Do I want to renovate immediately?
A new kitchen or bathroom can make a big difference in the required budget.
3. Do I want to make the home more sustainable?
Include these costs directly in the planning.
4. What monthly payment feels comfortable?
Don’t just look at what is possible. Look especially at what feels right.
5. What plans do I have for the next ten years?
Think of:
• Living together
• Children
• Working less
• Early retirement
• Self-employment
These choices influence the affordability of your mortgage.
Conclusion: look beyond the asking price
The purchase price of a home is only the beginning. Purchasing costs, mortgage advice, appraisals, sustainability, furnishing, and maintenance ultimately determine what a home really costs.
Those who gain insight into these invisible purchase costs beforehand avoid financial surprises, maintain a sufficient buffer, and make better-informed choices. After all, buying a home is not just a financing issue. It is a decision that affects your financial situation and living comfort for years to come.
Free purchase cost check at Pandomo
Are you looking for a home or have you just made an offer? Have the amount of your own money you actually need calculated in advance. This way, you know exactly where you stand and can make a decision with confidence.
Schedule a non-binding consultation with Pandomo and discover what your dream home really costs.